- Retrieve the foreign exchange (FX) rate before a transaction is performed.
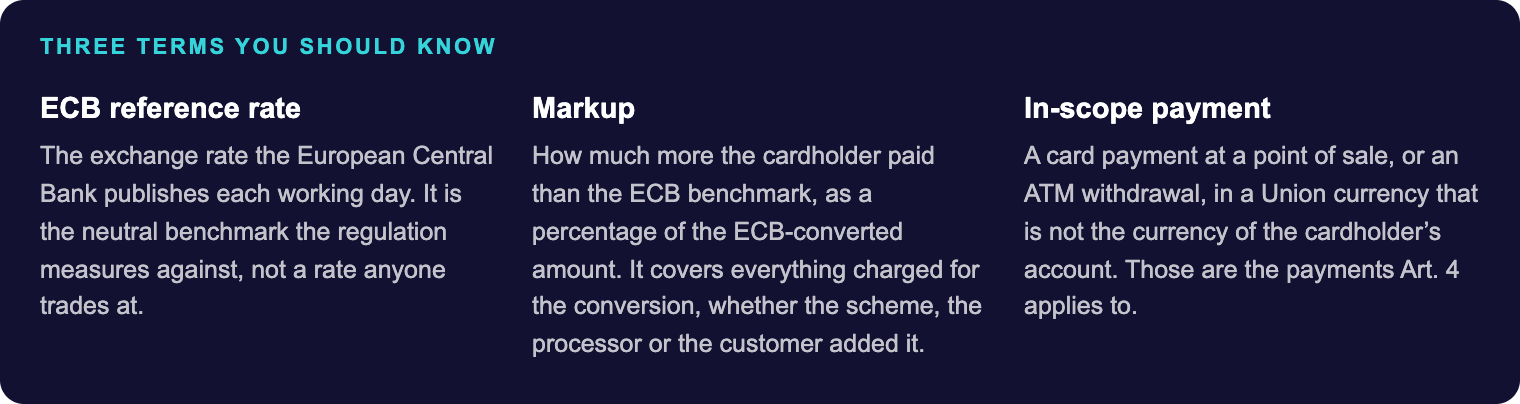
- Retrieve the European Central Bank (ECB) reference rate for an authorised transaction, so you can calculate the currency conversion markup to disclose to the cardholder.
The Exchange Rates API is an additional paid feature. To request access, contact Enfuce Support.
Pre-Transaction | Exchange Rates API
Before a transaction is processed, you can send requests to the Exchange Rates API and perform the following operations:| Operation | Endpoint |
|---|---|
| Retrieve the Visa/Mastercard supported Foreign Exchange (FX) rate conversion from a specific currency to another | FX Exchange Rates for Supported Card Schemes |
| Retrieve the list of currencies that European Central Bank (ECB) supports | ECB Supported Currencies |
| Retrieve the ECB rate conversion from one currency to another | ECB Exchange Rates |
fxRatePaymentScheme: The card scheme levied exchange rate.fxRateWithMarkup: The FX rate, including the issuer’s markup fee.fxRateEcb: The ECB exchange rate.markupPercentageOverEcb: The percentage difference between the ECB reference rate and the exchange rate applied to the cardholder, including the scheme’s exchange rate fee and the issuer’s markup.
The ECB updates its reference rates every working day around 16:00 CET. See ECB Reference Exchange Rates.
Alternative: link to the card scheme’s published rates
If you do not add a markup of your own to the card scheme’s exchange rate, you can meet the pre-transaction disclosure requirement without the Exchange Rates API. Link cardholders to the exchange rates the card scheme publishes, and place the link where they can reach it before paying, for example in your app or on your website.Post-Transaction | Transaction Event Webhook
When an initial or incremental authorisation is processed, whether approved or declined, asynchronous webhook notifications are sent to the ledger, including thetransaction.exchangeRates object. This object contains ecbRate, the latest ECB exchange rate available at the time of the authorisation. It is provided only when the cardholder’s billing currency is different from the transaction currency.
ecbRate is a reference rate, used to calculate the markup you disclose to the cardholder. It is not the exchange rate applied to the transaction.
What the message must contain
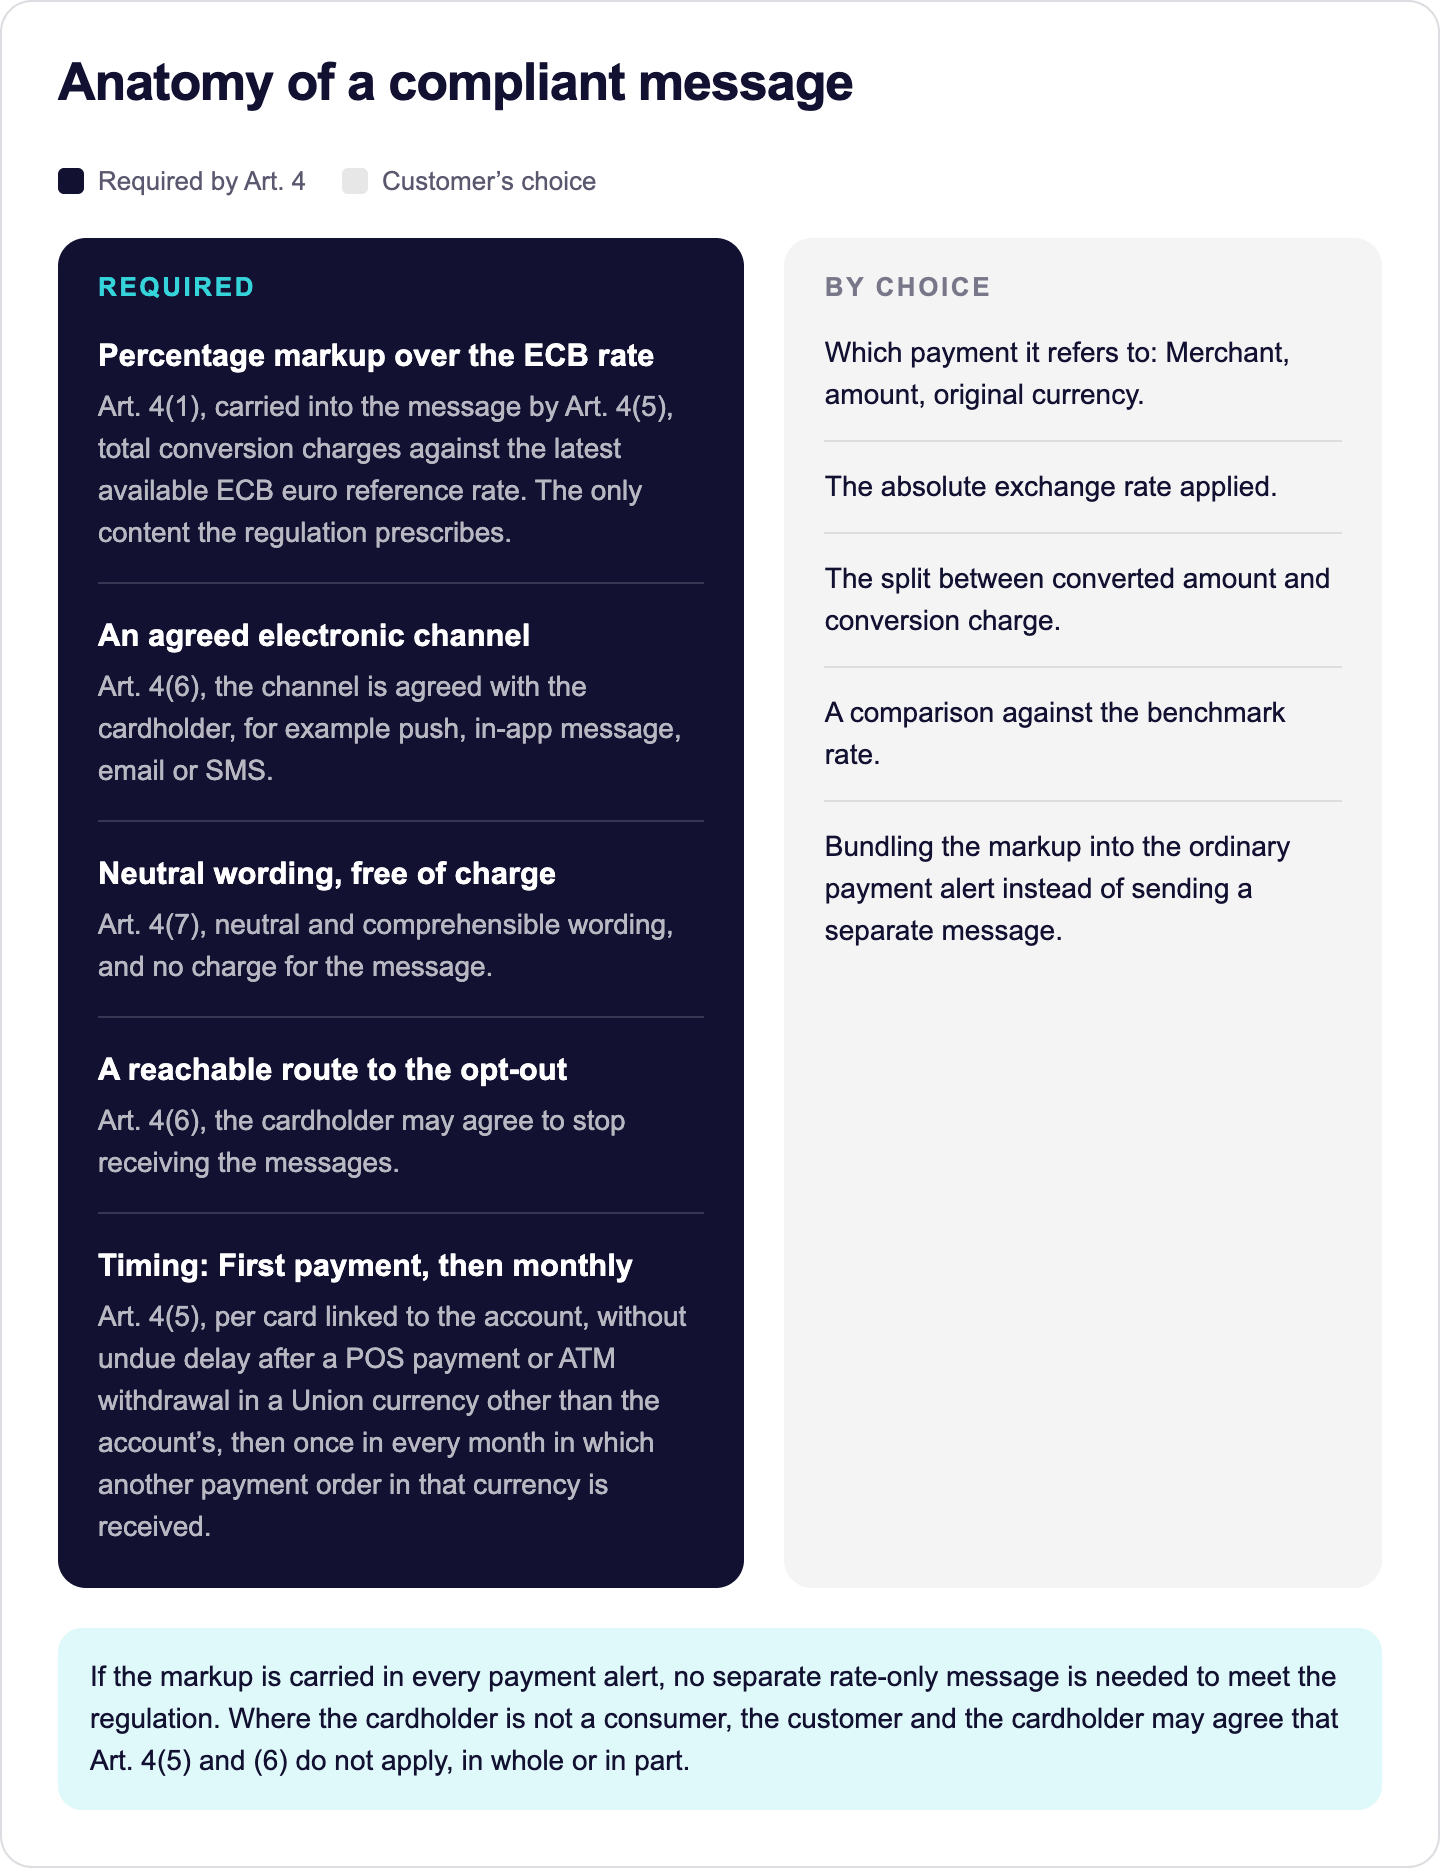
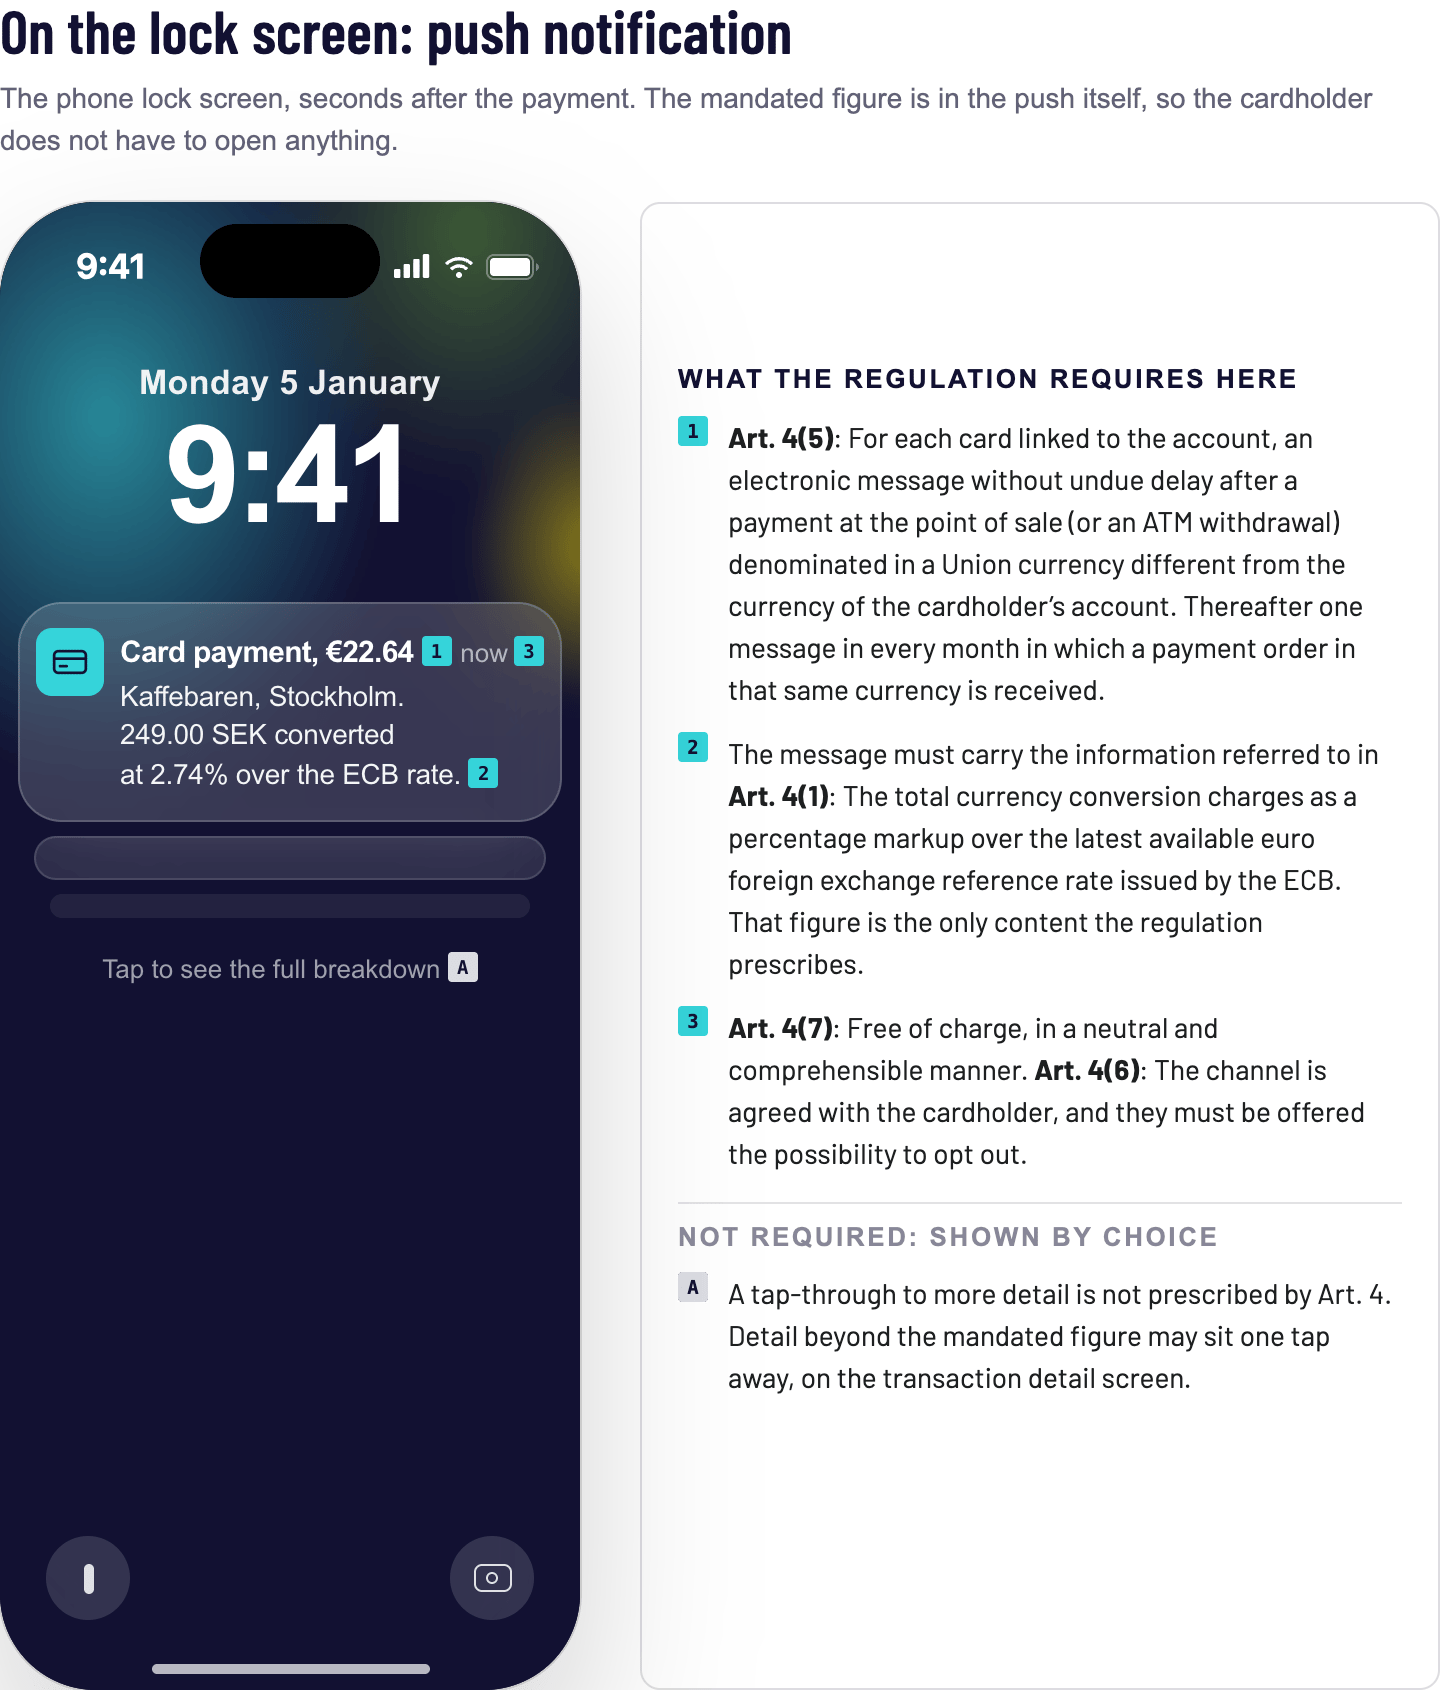
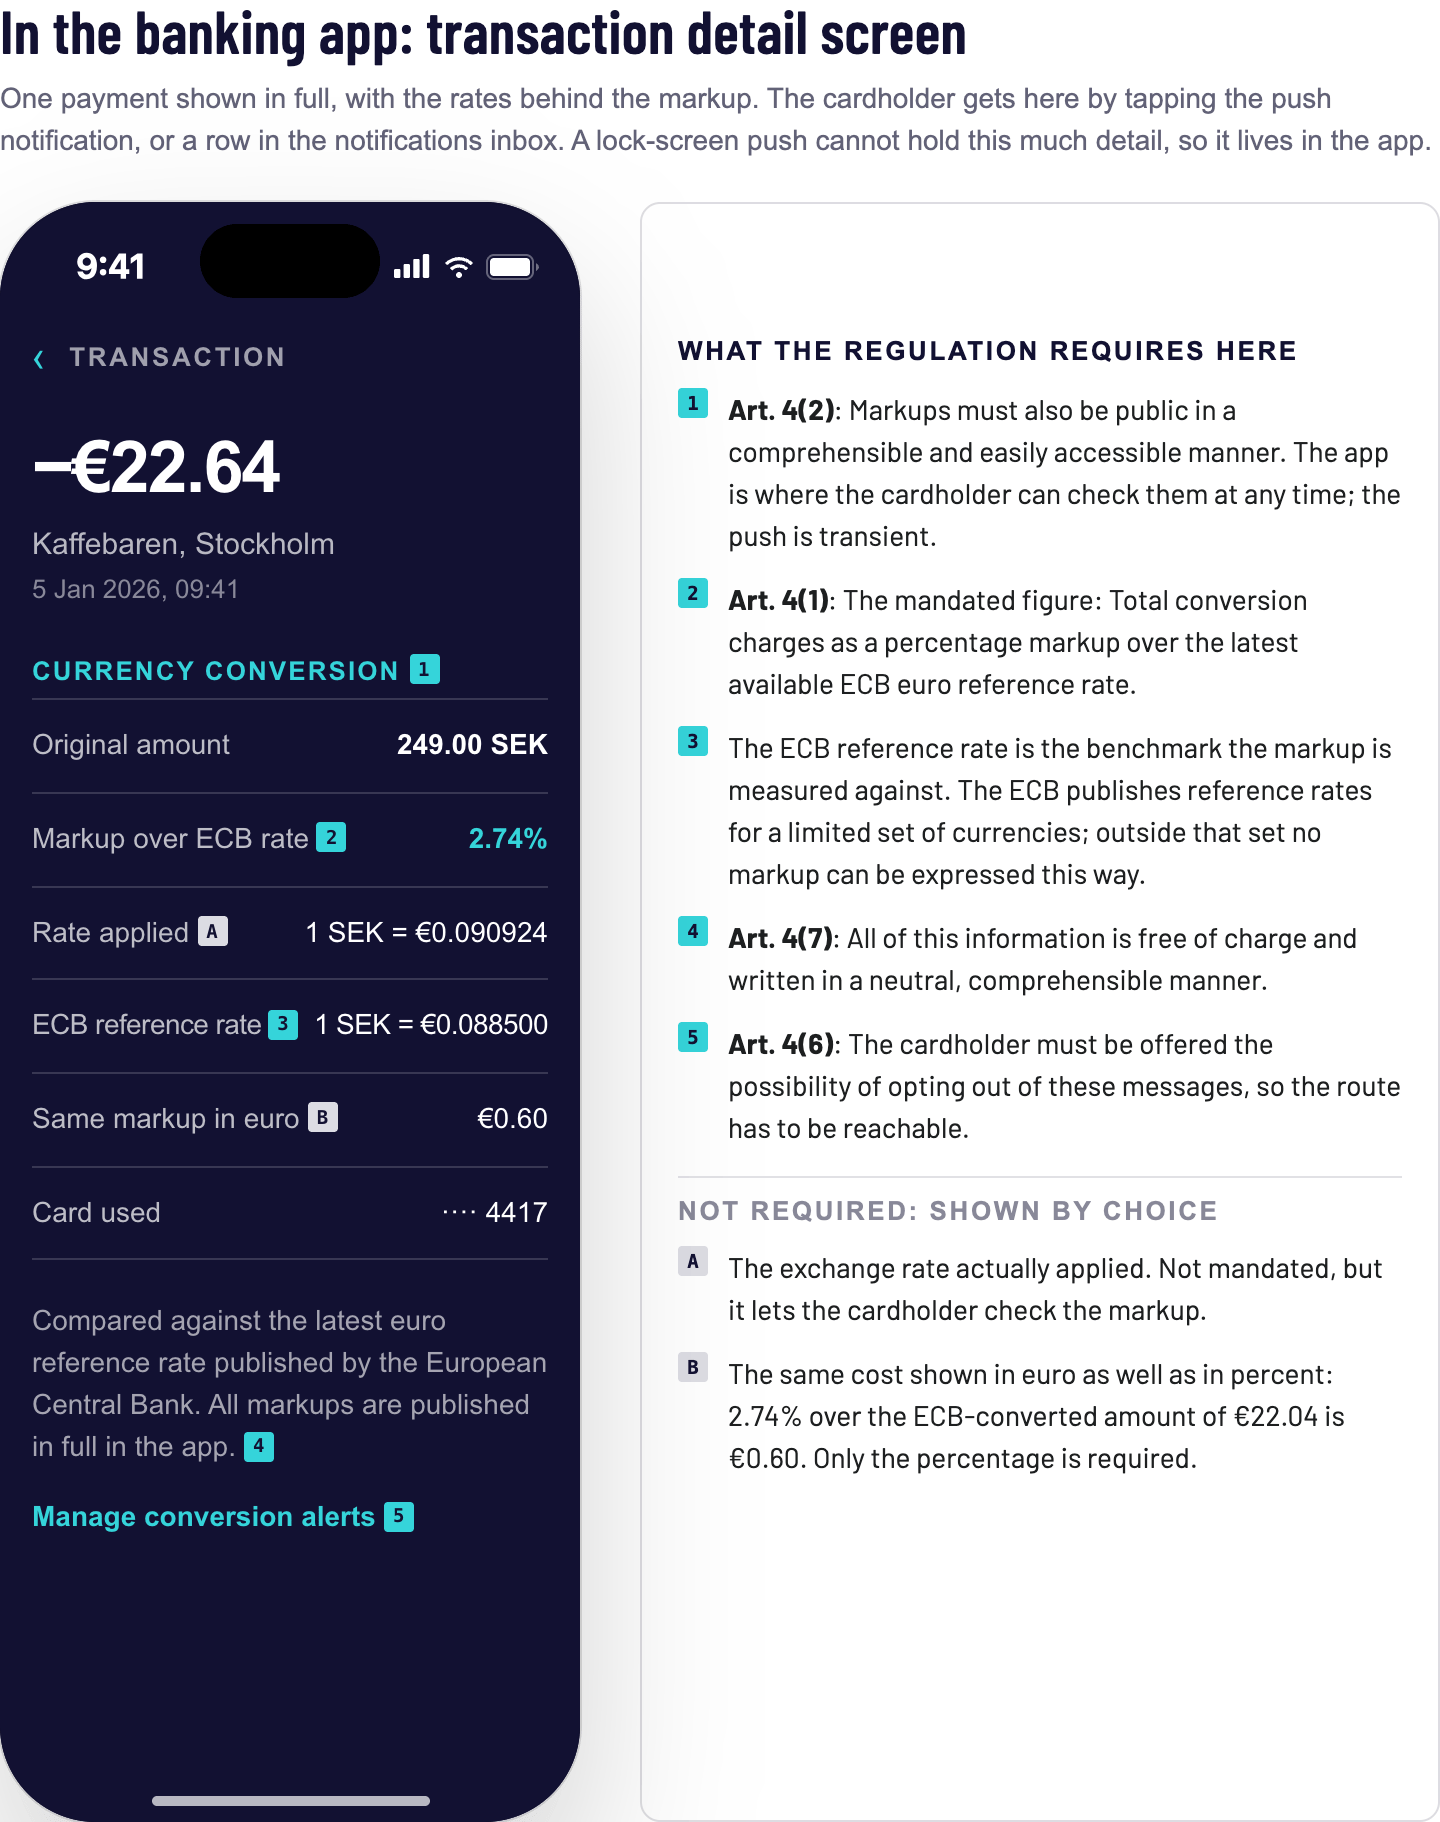
After an in-scope payment, the cardholder must receive an electronic message. An in-scope payment is a point-of-sale payment or ATM withdrawal in a Union currency that differs from the currency of the cardholder’s account. The regulation prescribes one figure for this message: the total currency conversion charge, expressed as a percentage markup over the latest available ECB euro reference rate (Article 4(1), carried into the message by Article 4(5)). Everything else is your choice to include, for example the merchant name, the original amount and the exchange rate applied.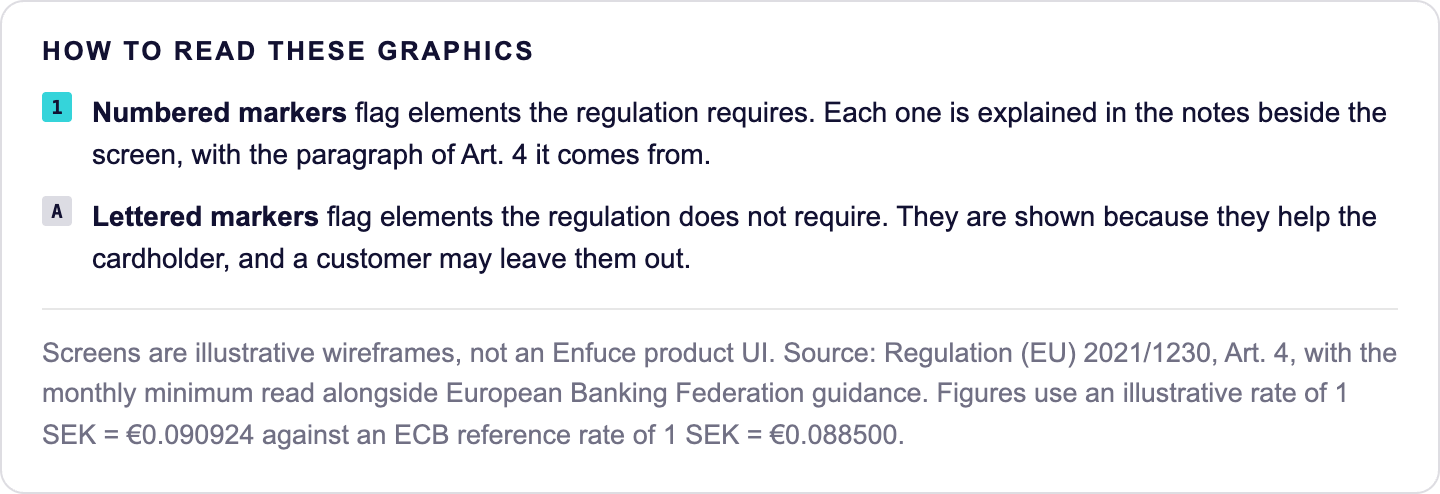
Calculating the markup
To calculate the markup from the authorisation event:- Take
billingAmount, the amount charged to the cardholder in their billing currency. It already includes your issuer fees. - For an ATM withdrawal or a cash disbursement, subtract the
ATM_FEEorCASH_FEEamount listed inissuerTransactionFees. These fees are not currency conversion charges. LeaveMARKUP_FEEin. - Divide the result by
transactionAmountto get the card exchange rate applied. - Divide the card exchange rate by
ecbRate, then subtract 1.ecbRateis expressed in the same way as the card exchange rate: units of the billing currency per one unit of the transaction currency.
Example messages
Customer’s Responsibility
BIN sponsorship customers: Enfuce is the card issuer of record and remains responsible to its regulator for compliance with CBPR. You must implement the disclosures described on this page for your cardholders before your programme goes live.
Self-sponsored BIN customers: You are the issuer under the regulation and hold this obligation directly with your regulator. This page is provided as implementation guidance, not an Enfuce-imposed requirement.
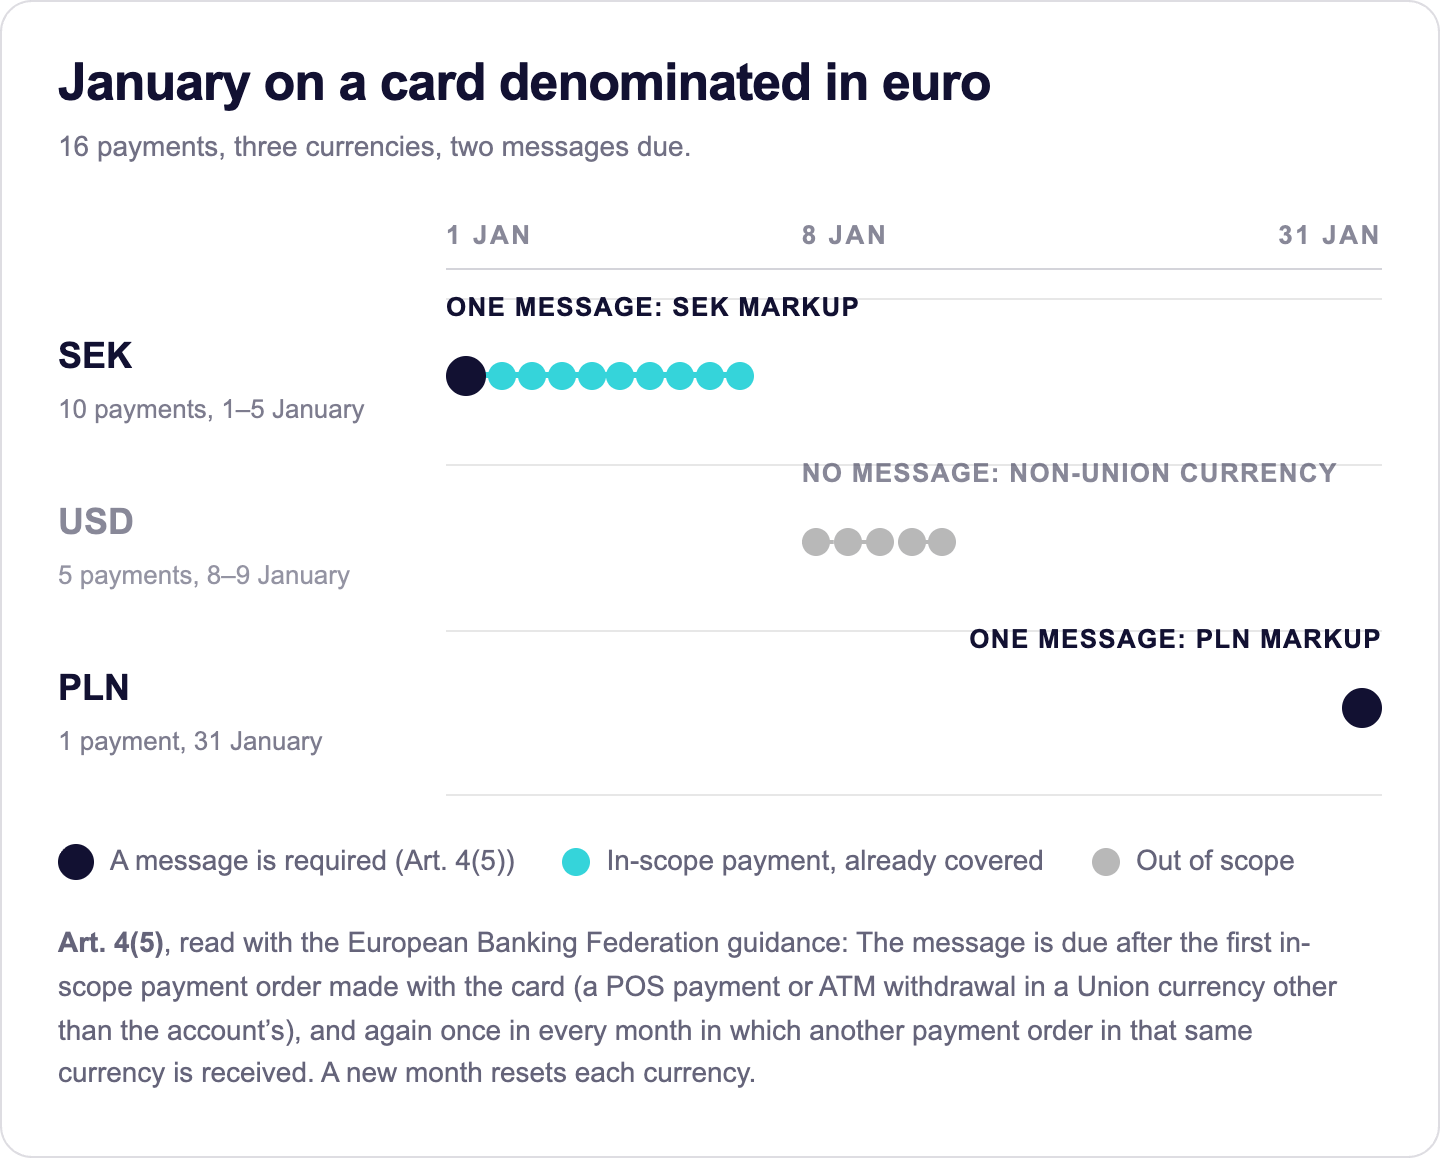
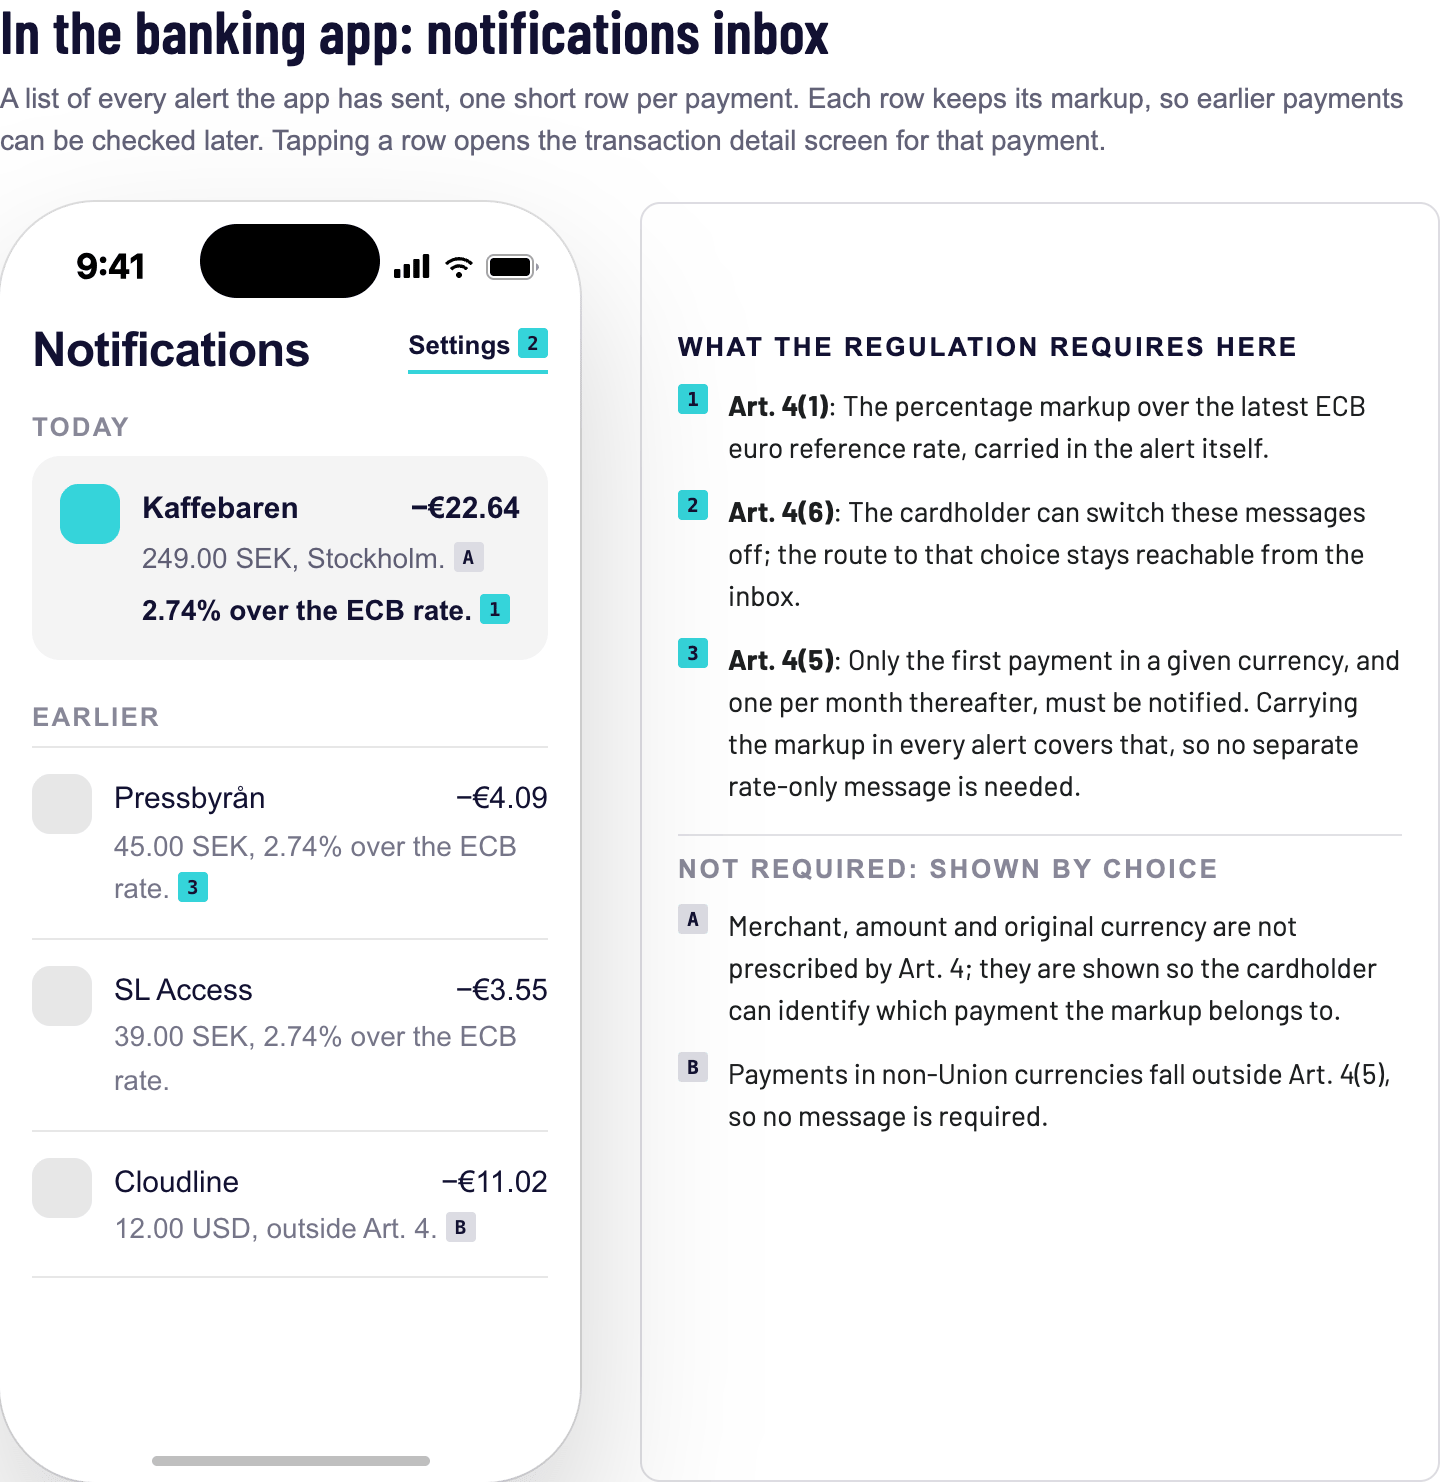
- The cardholder performs 10 transactions in Swedish Krona (SEK) between 1st and 5th January: Send one notification after the first authorisation informing the markup for the SEK > EUR exchange rate.
- The cardholder performs 5 transactions in United States Dollars (USD) on 8th and 9th January: No notification is required, as USD is not a Union currency and falls outside Article 4(5) of Regulation (EU) 2021/1230.
- The cardholder performs 1 transaction in the currency of Poland (PLN) on 31st January: Send one notification after the authorisation informing the markup for the PLN > EUR exchange rate.
Cross-Border Payments Regulation (CBPR) | Reference Documentation
This is for your reference, Article 4, Currency conversion charges related to card-based transactions, of Regulation (EU) 2021/1230:Article 4(1)
Article 4(1)
With regard to the information requirements on currency conversion charges and the applicable exchange rate, as set out in Article 45(1), Article 52, point (3), and Article 59(2) of Directive (EU) 2015/2366, payment service providers and parties providing currency conversion services at an automated teller machine (ATM) or at the point of sale, as referred to in Article 59(2) of that Directive, shall express the total currency conversion charges as a percentage mark-up over the latest available euro foreign exchange reference rates issued by the European Central Bank (ECB). That mark-up shall be disclosed to the payer prior to the initiation of the payment transaction.
Article 4(2)
Article 4(2)
Payment service providers shall also make the mark-up referred to in paragraph 1 public in a comprehensible and easily accessible manner on a broadly available and easily accessible electronic platform.
Article 4(5)
Article 4(5)
The payer’s payment service provider shall, for each payment card that was issued to the payer by the payer’s payment service provider and that is linked to the same account, send to the payer an electronic message with the information referred to in paragraph 1, without undue delay after the payer’s payment service provider receives a payment order for a cash withdrawal at an ATM or a payment at the point of sale that is denominated in any Union currency that is different from the currency of the payer’s account.Notwithstanding the first subparagraph, such a message shall be sent once every month in which the payer’s payment service provider receives from the payer a payment order denominated in the same currency.
Article 4(6)
Article 4(6)
The payment service provider shall agree with the payment service user on the broadly available and easily accessible electronic communication channel or channels through which the payment service provider will send the message referred to in paragraph 5.The payment service provider shall offer payment service users the possibility of opting out of receiving the electronic messages referred to in paragraph 5.The payment service provider and the payment service user may agree that paragraph 5 and this paragraph do not apply in whole or in part where the payment service user is not a consumer.
Article 4(7)
Article 4(7)
The information referred to in this Article shall be provided free of charge and in a neutral and comprehensible manner.